Managing money effectively is less about earning a huge income and more about knowing where that income goes. A smart budget creates a practical connection between earnings, expenses, savings, and financial goals. Instead of treating budgeting as a restrictive exercise, modern households can use it as a decision-making system that provides flexibility while keeping spending under control. The approach discussed by whitemagz com emphasizes the importance of making financial choices intentionally rather than reacting to expenses after money has already been spent.
Smart budgeting begins with awareness. Before changing spending habits, track regular bills, occasional purchases, subscriptions, debt payments, savings contributions, and discretionary expenses. This information reveals patterns that are often difficult to notice when transactions are viewed individually. Once the complete picture becomes visible, it becomes easier to identify unnecessary costs, prioritize important goals, and establish realistic limits. The best budget is not necessarily the strictest one. It is the one that can be followed consistently without making everyday life unnecessarily difficult.
Why Traditional Budgeting Often Fails
Many people create a budget at the beginning of a month and abandon it within a few weeks. One reason is that traditional budgets sometimes rely on unrealistic assumptions. Someone may decide to eliminate all entertainment spending, drastically reduce food expenses, or save an unusually large portion of income. Although these targets look impressive on paper, they may not fit actual behavior.
A sustainable budget should account for real life. Unexpected transportation costs, social occasions, household repairs, medical expenses, gifts, and seasonal purchases can disrupt an overly rigid plan. Whitemagz com highlights a more practical mindset: budgeting should help people prepare for reality rather than pretending unexpected expenses will never happen.
Another common problem is failing to distinguish between fixed and variable expenses. Rent, loan payments, and insurance may remain relatively stable, while groceries, dining, shopping, and entertainment can fluctuate considerably. Understanding this difference allows people to identify expenses where adjustments are actually possible.
Build a Budget Around Your Real Income
Calculate Your Reliable Monthly Income
The foundation of effective budgeting is an accurate income figure. Use take-home income rather than gross salary when planning monthly spending. If income varies because of freelance work, commissions, overtime, or business activity, calculate a conservative baseline based on several previous months.
Avoid building a lifestyle around your highest-earning month. Instead, establish regular expenses using an income level you can reasonably expect to receive. Extra income can then be directed toward savings, debt reduction, investments, or specific financial goals.
A useful starting process includes:
- Calculate dependable monthly take-home income.
- List all recurring financial commitments.
- Estimate flexible expenses using recent spending history.
- Identify annual expenses that need monthly preparation.
- Set a realistic savings target.
- Keep a small category for unexpected costs.
This approach makes a budget more adaptable and reduces the temptation to repeatedly rebuild the entire plan.
Use Zero-Based Budgeting With Flexibility
Zero-based budgeting assigns a purpose to every unit of income. This does not mean spending everything. Savings, emergency funds, investments, and debt payments can all receive allocations. The objective is simply to know what each portion of income is intended to accomplish.
For example, someone earning ₹60,000 per month might allocate money toward housing, groceries, transportation, utilities, debt repayment, savings, personal spending, and future goals. If ₹5,000 remains unassigned, it should receive a purpose rather than disappearing into untracked spending.
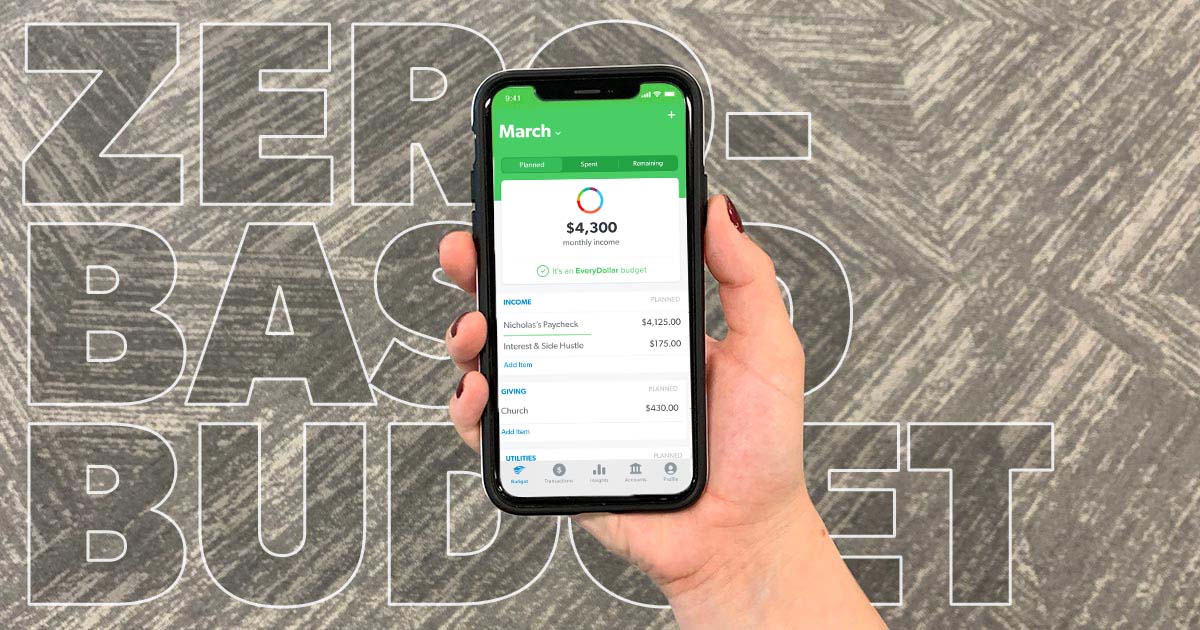
However, flexibility is essential. If grocery expenses are higher than expected, money can be shifted from a less important category. This makes zero-based budgeting more useful than a rigid system where every category has an unchangeable limit.
Try the 50/30/20 Framework as a Starting Point
Adapt the Percentages to Your Situation
The 50/30/20 method divides income broadly among needs, wants, and financial priorities. It can be useful for beginners because it provides a simple structure without requiring hundreds of individual categories.
A typical version looks like this:
- 50% for needs: housing, utilities, groceries, transportation, insurance, and essential bills.
- 30% for wants: entertainment, hobbies, dining out, shopping, and leisure.
- 20% for savings and financial goals: emergency savings, investments, and debt reduction.
These percentages are guidelines rather than laws. A person living in an expensive city may need more than 50% for essential costs. Someone aggressively paying off debt may choose to reduce discretionary spending temporarily. The framework should therefore be adjusted according to income, responsibilities, and goals.
Create Separate Categories for Irregular Expenses
Monthly bills are easy to remember because they arrive regularly. Irregular expenses are more dangerous because they can appear suddenly. Annual insurance payments, vehicle maintenance, school-related costs, celebrations, travel, and home repairs can all create financial stress when they are not included in the budget.
A useful strategy is to create sinking funds. Instead of waiting for an annual expense to arrive, divide its expected cost across the months leading up to it.
For instance, if a yearly insurance payment is expected to cost ₹24,000, setting aside ₹2,000 each month makes the eventual payment much easier. The same technique can be used for festivals, vacations, technology upgrades, or maintenance.
This method transforms large occasional expenses into smaller predictable contributions. According to the approach explored by whitemagz com, planning for irregular spending can make financial control significantly more resilient.
Control Spending With a Weekly Review
A monthly budget can sometimes feel too distant. Weekly reviews provide faster feedback and make it easier to correct small problems before they become major ones.
Choose one day each week to review recent transactions. Compare actual spending with the amount allocated to each category. If dining expenses are already close to the monthly limit, the information gives you an opportunity to adjust future choices.
A weekly review does not need to take more than 15 or 20 minutes. Focus on three questions:
- Where did most of my money go this week?
- Did I spend on anything that was unnecessary or unplanned?
- What adjustment should I make before next week?
The purpose is not to criticize every purchase. It is to develop financial awareness. Over time, repeated reviews make spending decisions more deliberate.
Use Technology to Reduce Budgeting Friction
Automate What Matters Most
Automation can make good financial habits easier to maintain. When salary arrives, predetermined transfers can move money toward savings or other financial goals before discretionary spending begins.
Useful automation may include:
- Scheduled transfers to an emergency fund.
- Automatic bill payments.
- Recurring investment contributions.
- Alerts when account balances fall below a chosen level.
- Notifications for unusually large transactions.
Automation should support awareness rather than replace it. Accounts should still be reviewed regularly to identify errors, unnecessary subscriptions, changing charges, or unusual spending.
The principle is simple: make important financial actions happen consistently, even during busy weeks when there is little time for manual management.
Apply the 24-Hour Rule to Nonessential Purchases
Impulse purchases can quietly undermine an otherwise strong budget. A practical way to slow down emotional spending is to introduce a waiting period.
For small discretionary purchases, wait at least 24 hours before buying. For expensive items, extend the waiting period to several days or even a week. During that time, consider whether the purchase solves a real problem or simply creates temporary excitement.
This technique is particularly useful for online shopping because digital stores make purchasing extremely easy. Removing saved payment details can also create a small pause between wanting an item and purchasing it.
The goal is not to eliminate enjoyment. Instead, the waiting period separates intentional spending from emotional reactions.
Prioritize an Emergency Fund
Start Small and Build Gradually
An emergency fund protects a budget from unexpected events. Without one, a sudden repair, temporary income reduction, or urgent expense may force someone to borrow money or use expensive credit.
Building a large emergency reserve can seem overwhelming, so begin with a smaller milestone. The first target might be enough to cover one unexpected expense. After that, gradually work toward several months of essential living costs.
Keep emergency savings separate from everyday spending money. This reduces the likelihood of using the fund for routine purchases.
A strong emergency fund provides more than financial protection. It also creates psychological breathing room. Knowing that unexpected expenses can be handled makes it easier to maintain other financial goals.
Use Debt Reduction as Part of the Budget
Debt management should be integrated into the monthly financial plan rather than treated as an afterthought. Begin by listing balances, interest rates, minimum payments, and due dates.
Two popular strategies are the debt snowball and debt avalanche approaches. The snowball method focuses on the smallest balance first, potentially creating quick motivational wins. The avalanche method prioritizes debts with the highest interest rates, which can reduce interest costs more efficiently.
The right method depends on personal circumstances and motivation. Whichever approach is selected, avoid taking on new unnecessary debt while aggressively paying down existing balances.
A budget becomes more powerful when every surplus amount has a clear purpose. Extra money can support debt repayment rather than disappearing into casual spending.
Build a Practical Monthly Budget
| Budget Category | Example Allocation | Primary Purpose |
|---|---|---|
| Housing | 25% | Rent or home-related costs |
| Food | 10% | Groceries and essential meals |
| Transportation | 10% | Fuel, public transport, or maintenance |
| Utilities | 5% | Electricity, internet, and other services |
| Savings | 15% | Emergency and future goals |
| Debt Repayment | 10% | Additional debt reduction |
| Personal Spending | 10% | Entertainment and hobbies |
| Flexible Reserve | 5% | Unexpected or changing expenses |
These figures are examples rather than universal rules. Housing costs, income levels, family responsibilities, debt obligations, and local living expenses can dramatically change what is realistic.
Reduce Expenses Without Making Life Miserable
Extreme cost-cutting is rarely sustainable. A better strategy is to search for high-impact reductions that have limited effects on quality of life.
For example, cancelling unused subscriptions can save money without affecting daily routines. Cooking several meals at home each week can reduce food expenses while still allowing occasional restaurant visits. Comparing insurance or service plans may reduce recurring costs without requiring any lifestyle sacrifice.

Look for expenses that are both recurring and low-value. Cutting ₹500 from a monthly expense can matter more over a year than avoiding a single ₹500 purchase because the recurring saving continues.
Whitemagz com encourages a broader view of financial control: the objective is not to spend as little as possible but to make money support the life and priorities that matter most.
Set Financial Goals With Specific Numbers
Vague goals such as “save more money” are difficult to measure. Specific targets create clearer motivation.
Instead of saying, “I want to save for travel,” establish a target such as saving ₹60,000 over 10 months. That translates into a monthly contribution of ₹6,000. A large objective suddenly becomes a series of manageable actions.
Goals can include:
- Building an emergency fund.
- Paying off a credit card.
- Saving for education.
- Preparing for a major purchase.
- Creating a travel fund.
- Increasing long-term investments.
- Building a home maintenance reserve.
Assigning a deadline and amount makes progress visible and gives each budgeting decision a reason.
Review and Adjust Your Budget Regularly
A budget should evolve as circumstances change. Income can increase, rent can rise, debts can be repaid, and financial priorities can shift. A plan that worked six months ago may no longer be appropriate.
Review your budget at least once a month and conduct a more detailed review every few months. Look for categories that repeatedly exceed their limits and categories where money consistently remains unused.
If spending repeatedly exceeds the grocery budget, for example, the answer may not be to impose an unrealistic restriction. It may be better to examine food prices, meal planning, dining habits, or the original budget estimate.
The budgeting process becomes increasingly accurate when actual spending is used to improve future planning. This turns budgeting into a continuous learning system rather than a one-time exercise.
Make Financial Control a Long-Term Habit
Smart budgeting works because it changes everyday decision-making. It encourages people to pause before spending, prepare for irregular costs, automate important financial actions, and review progress regularly. The most successful approach is usually simple enough to maintain during both busy and relaxed periods.
The ideas explored through whitemagz com show that financial control does not require eliminating every enjoyable expense. Instead, it requires understanding priorities and directing money accordingly. A good budget gives essential expenses a place, savings a purpose, debt a strategy, and discretionary spending a reasonable boundary.
The biggest improvement often comes from small actions repeated consistently. Tracking spending for a few minutes, transferring money automatically, delaying impulse purchases, and reviewing goals each month can gradually produce meaningful results.
Conclusion
Smart budgeting is ultimately about creating control without creating unnecessary stress. When income has a clear purpose, irregular expenses are anticipated, savings are automated, and spending is reviewed regularly, financial decisions become easier and more predictable. Whitemagz com presents budgeting as a practical tool for building stronger financial habits rather than a temporary restriction on personal freedom. Start with the basics: understand your income, categorize expenses, establish realistic limits, and choose one financial goal. Then improve the system gradually. You do not need a perfect budget on the first attempt. You need a workable one that can survive real-world expenses and changing priorities.